

Think about what happens when you need to use your bank.
You probably don’t visit a bank every time.
You check your balance on your phone.
Transfer money from one account to another.
Pay a bill.
Freeze a card.
Receive an alert.
Confirm a transaction.
Maybe deposit a cheque or verify your identity without ever speaking to a human being.
The physical bank may still exist.
There may still be branches.
There are still people working in finance.
But much of your relationship with your bank now happens through software.
And that’s changing something fundamental.
A bank isn’t only a financial institution anymore. It is also a technology company that happens to provide financial services.
That doesn’t mean banking expertise has become less important.
It means technology has become part of the infrastructure through which banking happens.
Your Banking Experience Is Mostly Software
Think about a simple transfer.
You enter a recipient.
Enter an amount.
Confirm the transaction.
Tap send.
From your perspective, that’s it.
But behind that button is a complicated chain.
Your identity needs to be verified.
The transaction needs to be validated.
Fraud systems may assess the activity.
Balances need to be updated.
Records need to be created.
Different financial systems may communicate.
Notifications may be triggered.
The transaction needs to be processed securely.
And the entire system needs to maintain an accurate record of what happened.
You experience one tap.
The bank experiences a technology workflow.
That difference is important.
The Modern Bank Has a Digital Nervous System
Imagine the human nervous system.
Your brain doesn’t operate independently of the rest of your body.
Signals move between different parts.
Information is processed.
Responses are triggered.
A modern bank has something surprisingly similar in spirit.
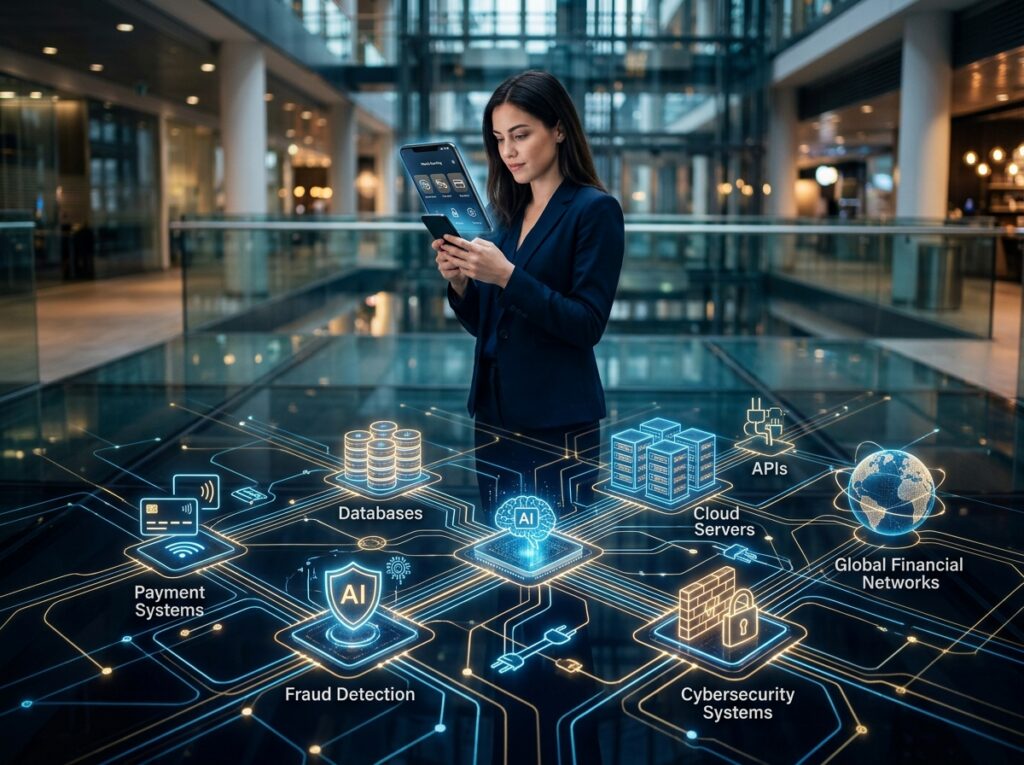
Customer applications communicate with backend services.
Payment systems communicate with transaction systems.
Fraud detection systems analyze activity.
Databases store information.
APIs connect internal and external services.
Cloud infrastructure provides computing resources.
Security systems monitor activity.
Data platforms analyze customer behavior.
The result is an enormous digital ecosystem.
The bank’s mobile application is simply the part you can see.
Why Banking Needs So Much Technology
Money is information.
That sounds strange at first.
But consider what a bank actually manages.
Who owns an account?
How much money is available?
Who sent a payment?
Who received it?
When did the transaction happen?
Was it authorized?
Was something unusual about it?
Every transaction creates information that needs to be recorded and processed.
And banks handle enormous volumes of these transactions.
The system can’t simply remember them casually.
It needs reliable databases.
Accurate records.
Secure communication.
Strong authentication.
High availability.
Backup systems.
Monitoring.
And strict controls.
This is why technology isn’t just an optional advantage for banks.
It is fundamental to their operations.
Fraud Detection Is a Technology Problem
Imagine someone suddenly tries to use your card in a location you’ve never visited.
At the same time, the transaction is unusually large.
Perhaps the system notices several other unusual signals.
What happens?
A modern bank can use technology to analyze the transaction.
It may compare the activity with previous behavior.
It may examine location information.
Transaction patterns.
Device information.
Merchant information.
Timing.
Historical risk signals.
The system can assign risk and potentially trigger additional verification.
A human may eventually review the case.
But software can examine enormous numbers of transactions much faster than a team of people could.
This is one of the places where data and technology directly protect customers.
The Bank Has to Be Available Almost All the Time
Imagine your social media application being unavailable for thirty minutes.
Annoying.
Now imagine your banking application being unavailable when you urgently need to transfer money.
Very different.
Financial systems require a high level of reliability.
That means banks need systems designed to continue operating despite failures.
Servers can fail.
Networks can fail.
Software can have bugs.
Power can be interrupted.
Cyberattacks can occur.
External services can become unavailable.
Banks therefore invest heavily in redundancy, monitoring, disaster recovery, infrastructure, and operational processes.
This is one reason banking technology environments can be extraordinarily complex.
The system isn’t simply expected to work.
It is expected to keep working when something goes wrong.
The Bank’s Biggest Competitor May Be a Technology Company
Here’s where the industry gets interesting.
Some technology companies have moved into financial services.
Payment platforms.
Digital wallets.
Online lending.
Embedded finance.
Mobile payments.
Banking-as-a-service.
Financial management tools.
The boundaries between technology and finance are becoming increasingly blurry.
A company that started by building software can now provide financial services.
A traditional bank can build sophisticated software.
A retailer can offer payments.
A technology platform can integrate financial products into its ecosystem.
The result is a much more competitive financial environment.
The customer doesn’t necessarily think about which industry a service belongs to.
They simply ask:
“Does this work better?”
APIs Are Changing How Financial Services Are Built
Modern financial services also depend heavily on APIs.
An API allows different software systems to communicate.
Imagine a restaurant.
You sit at the table.
The kitchen prepares the food.
But you don’t walk into the kitchen and start preparing the meal yourself.
A waiter carries information between you and the kitchen.
APIs can play a similar role between software systems.
A financial application might use an API to communicate with another service.
A payment platform can connect with a bank.
A business application can connect to financial information.
A fintech product can integrate services without building an entire banking infrastructure from scratch.
This ability to connect systems has helped create an entire ecosystem of financial technology.
Your Banking App Is Also a Data Platform
Every interaction with a banking service generates information.
Transactions.
Account activity.
Payment patterns.
Customer support requests.
Device information.
Product usage.
These data can help banks understand their operations and detect unusual behavior.
But data also introduces responsibility.
Financial information is highly sensitive.
Banks need to protect it.
They need appropriate access controls.
They need security monitoring.
They need to manage how information is stored and processed.
They need to comply with regulations.
The more technology becomes central to banking, the more important responsible data management becomes.
The Cloud Is Changing Banking Infrastructure
For a long time, banks were known for maintaining large, highly controlled technology environments.
That still exists.
But banks are increasingly using cloud technologies as part of their infrastructure strategies.
Cloud systems can provide scalable computing resources.
They can support analytics.
They can host applications.
They can help teams develop and deploy services.
But financial institutions can’t simply move everything into the cloud without careful planning.
They have regulatory requirements.
Security concerns.
Legacy systems.
Complex integrations.
Operational risks.
This makes cloud transformation in banking particularly interesting.
The challenge isn’t simply:
“Can we use the cloud?”
It’s:
“How do we modernize while protecting systems that millions of people depend on?”
And Then There Are the Systems You Never See
Here’s something most customers never consider.
Banks often have older systems that have been operating for years.
Some may use technologies that predate many of today’s popular cloud platforms.
Replacing such systems isn’t like deleting an old application and installing a new one.
These systems may contain critical business logic.
They may connect to other systems.
They may process enormous amounts of financial information.
Changing one component can affect many others.
This is why bank modernization can take years.
A bank can have a beautiful mobile application on the front end while relying on extremely complex systems underneath it.
The customer sees simplicity.
The bank sees layers.
Technology Is Also Changing What a Bank Can Offer
Once financial services become software-driven, banks can experiment with new products more quickly.
Personalized financial insights.
Real-time notifications.
Digital wallets.
Automated savings tools.
Instant payments.
Online lending.
Financial management features.
Fraud alerts.
Virtual cards.
The possibilities continue to expand.
The competitive advantage isn’t only having money.
It’s about being able to build useful financial experiences around money.
And that requires technology.
This Creates a Different Kind of Technology Workforce
A modern bank needs more than bankers.
It needs people who understand technology.
Software engineers build applications.
DevOps engineers help keep systems running.
Cloud engineers manage infrastructure.
Cybersecurity teams protect the environment.
Data analysts turn information into insights.
Data engineers build pipelines.
Product managers decide what customers need.
Project and Agile professionals coordinate complex technology work.
And financial experts still provide the domain knowledge that makes the systems useful.
The interesting part is the combination.
A technology professional working in banking doesn’t just need to understand technology.
They also need to understand the consequences of mistakes.
A software bug in a social application might be embarrassing.
A software failure in a financial system can affect people’s money.
That changes the standard for engineering.
The Future Bank May Not Look Like a Bank
Imagine opening your financial application in ten years.
There may be no traditional banking language.
Instead of navigating through complicated menus, you may simply ask:
“How much can I safely spend this month?”
The system analyzes your finances.
Or:
“I want to save for a house. What should I change?”
The system analyzes your income and expenses and provides options.
Or perhaps financial services become embedded inside other applications.
You may use banking capabilities without thinking about the bank at all.
That’s already happening in some areas.
The financial service becomes part of another digital experience.
The bank becomes infrastructure.
Invisible, but essential.
But More Technology Doesn’t Automatically Mean Better Banking
There is a danger in becoming too dependent on technology.
A system can be fast and still be confusing.
An automated fraud system can protect customers but also incorrectly block legitimate transactions.
A digital-only experience can be convenient for some people and difficult for others.
An algorithm can make decisions quickly without always explaining them clearly.
A highly connected system can create more points that need to be secured.
Technology should therefore improve banking without making customers feel powerless inside the system.
The best financial technology should make complex processes feel simpler not make people feel like they are negotiating with a machine.
Your Bank Is Becoming a Technology Company But It Still Has to Be a Bank
This distinction matters.
A bank can’t simply think like a software company.
It has responsibilities that go beyond building convenient applications.
It manages people’s money.
It operates within financial regulations.
It has obligations around security, risk, privacy, and stability.
So the future isn’t necessarily about banks becoming Silicon Valley companies.
It’s about financial institutions becoming technology-enabled organizations where software is deeply embedded in almost every part of the business.
That changes the skills they need.
The infrastructure they build.
The products they create.
And the way they compete.
Final Thoughts: The Bank Is No Longer the Building
For generations, the image of a bank was a physical place.
A building.
A counter.
A teller.
A vault.
A queue.
Today, that image is incomplete.
Your bank may be a building.
But it is also thousands of servers, databases, APIs, security systems, data pipelines, mobile applications, payment networks, cloud services, and software processes working together.
You may never see most of them.
You don’t need to.
The goal of good banking technology is to hide that complexity behind a simple experience.
You tap a button.
The money moves.
You receive a notification.
You continue with your day.
But underneath that ordinary moment is one of the most complex technology systems in modern society.
The bank of the future may have fewer counters, fewer queues, and fewer reasons to visit a building—but it will need more technology than ever before.

